● Quantitative Research Studio
GraviRefract 引力折射
Researching factor & model decay and overfitting.
Research · Backtests · Live feedback
Research Reports
View all →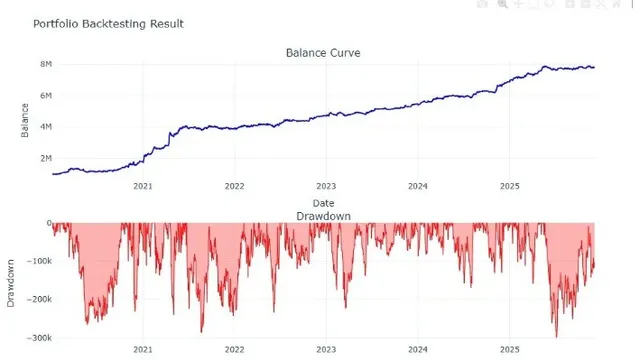
Linear Weighted Multi-Factor Model (Non-Machine-Learning)
Before machine-learning, complete factor feature engineering via linear weighting: 22 Binance USDT-perpetual contracts, 2020–2025 six-year backtest — +679.79% return, 19.21% max drawdown, return/drawdown ratio 22.72, with year-by-year equity curves.
Crypto Multi-Factor Strategy: LSRATIO & TAKER
Two crypto factors — LSRATIO (top-trader long/short position ratio) and TAKER (active taker buy/sell ratio): signal principles and a 6-year backtest comparison, return-to-drawdown ratio 21.65 → 27.92 (+29%).
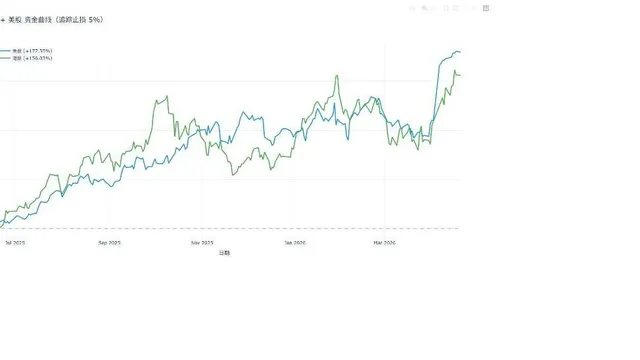
News Sentiment Strategy: Complete Research Report
Complete research of the news sentiment factor: IC/ICIR verifies sentiment is a lagging indicator → contrarian strategy → news + volume dual filter → momentum re-optimization. 10-month HK/US backtest excess return +28.93% / +36.47%; HK + momentum lifts return/drawdown to 7.29.
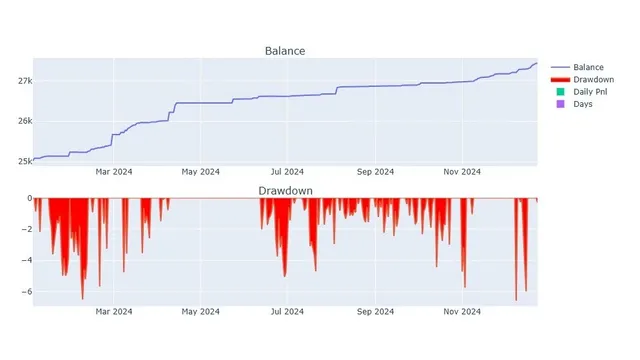
Stocks / Crypto / Forex: Backtest & Live Trading Report (2025)
Three lines: XPEV daily backtest (12.7M profit, 38% annualized), BTC/ETH futures trend strategies (47,500 USDT live test, annualized return/drawdown 6.05 / 7.32) and CEX–DEX spread arbitrage (no-leverage return/drawdown 376); plus ETH/SOL grid live trading on Ubuntu, MT5 Python development and FinGPT news sentiment exploration. Ongoing live records live in the Track Record section.
Quant System
View all →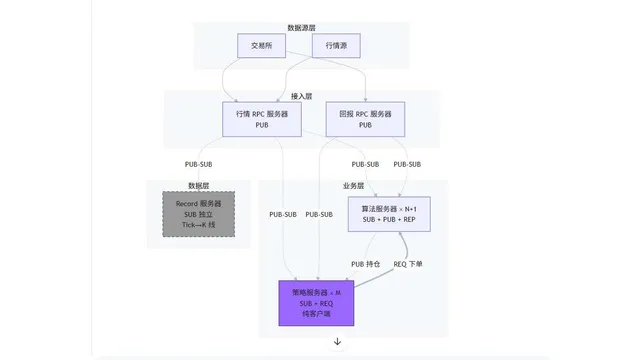
Architecture Refactoring: Core Service Components & Live Front-Ends
Quant system architecture refactoring: market-data / trade-return RPC broadcast, two-tier algorithm & strategy services, five core data flows, plus the web and mobile front-end interfaces of the live trading system.
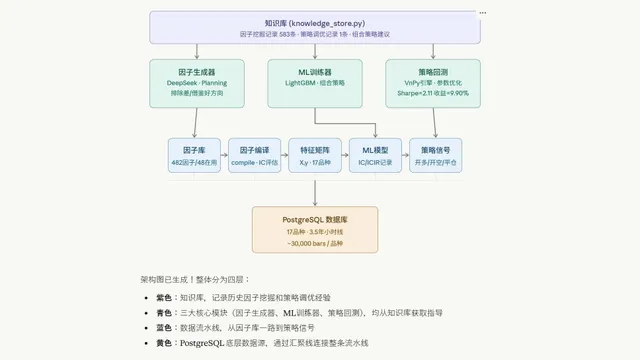
Multi-Agent System & Event-Driven Strategy Architecture
The five-stage financial event-driven pipeline (collection → extraction → events → fusion → impact analysis) and the multi-agent system's initial architecture (knowledge base + factor generation / ML training / strategy backtest), with the system flowchart and a single-stock backtest.
OpenClaw Sentiment Assistant Work Report
OpenClaw-based social-media sentiment monitoring: conversational operation end-to-end, news collection, Zhipu embedding-2 semantic clustering (Leader algorithm, threshold 0.85), popularity ranking and Feishu push — Python standard library only, zero external dependencies.